Gold is highly volatile right now. In fact, it fluctuates in response to news about liquidity. On some trading days, announcements about the Fed’s purchases of T-bills, changes in bank reserves, or Treasury refinancing are interpreted as a sign that the authorities will continue to provide sufficient liquidity to the financial system, and gold surges sharply higher. At other times, long-term rates take the upper hand: Treasury yields rise, the dollar strengthens, the cost of capital increases, and gold corrects almost as quickly.
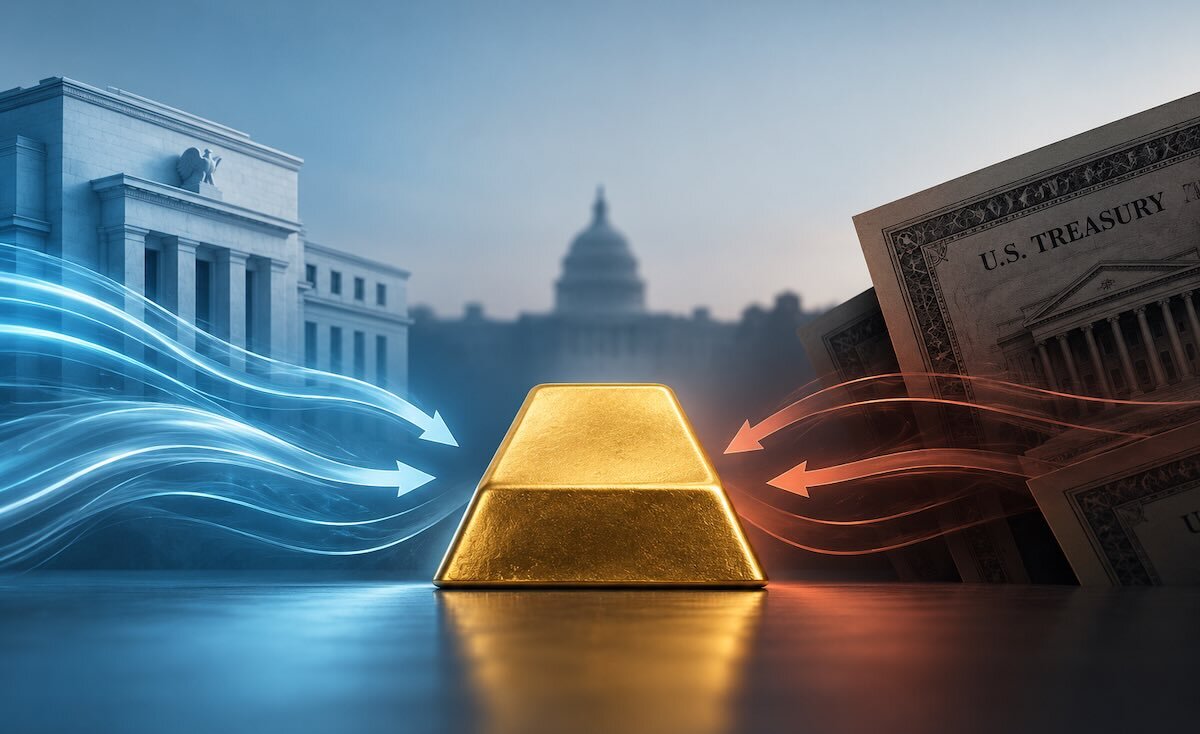
This volatility may give the impression that the gold market is no longer quite sure which story to tell. On the contrary, I believe it reflects fairly accurately what is actually happening. Two forces are now acting simultaneously on liquidity, but in opposite directions.
The first is positive: the Fed is absorbing T-bills and providing reserves to the banking system in exchange. The second is negative: rising long-term rates are driving down the value of existing bonds, weighing on the balance sheet capacity of certain financial intermediaries, increasing the cost of financing, and attracting a growing amount of capital to the bond market.
Gold lies exactly between these two forces.
A debt that must be continually refinanced
The first part of the problem lies with the U.S. Treasury. More than $7 trillion in T-bills are now in circulation, and by definition, this very short-term debt must be continually refinanced. Next week provides a striking illustration of this: the Treasury must issue $354 billion in debt in just four days, including $171 billion in three- and six-month T-bills.
Of course, this $354 billion should not be confused with an equal amount of new debt. A significant portion of these issuances is simply used to replace maturing securities. But that is precisely what makes the situation interesting: the more the debt is concentrated in short maturities, the more frequently the Treasury must return to the market to refinance the same amounts — to which are then added the financing needs associated with new deficits.
It is in this context that we must understand the Fed’s return to the T-bill market:

The Fed presents these operations as a tool for managing bank reserves, not as a new monetary stimulus program comparable to the large-scale QE programs that followed the 2008 crisis. Technically, this distinction is important. When the Fed purchases a Treasury bond, it does not directly distribute money to households: it essentially exchanges a financial asset held by the private sector for bank reserves — that is, a much more liquid form of central bank money.
By absorbing a portion of these securities and maintaining a sufficiently high level of reserves, the Fed helps prevent the Treasury’s massive financing needs from draining too much liquidity from the rest of the financial system. It is therefore not simply a matter of saying that “the Fed is printing money.” It helps keep the financial system liquid as it must absorb and refinance ever-increasing volumes of debt.
This is the primary driver.
Two contrasting forms of liquidity
The problem is that creating reserves is not necessarily enough to generate liquidity.
A bank does not lend simply because it has reserves. It must also have sufficient capital and balance-sheet capacity to take on more risk. However, rising long-term interest rates can actually erode that capacity at the very moment the Fed is adding reserves to the system.
When a bond yield rises, the price of the corresponding bond falls. For a bank that holds large portfolios of Treasuries or MBS classified as Available For Sale, this decline is recognized in Other Comprehensive Income and then accumulates in AOCI. This is not necessarily a realized loss, but the decline in value is immediately reflected in the portfolio’s market value and, for some large banks, may also affect regulatory capital.
The distinction between reserves and bank capital then becomes fundamental. A bank may have abundant reserves while becoming much more constrained in its use of the balance sheet.
And banks are only part of the problem. When long-term rates rise, the bonds held by insurers, pension funds, and bond funds also lose value. Volatility can increase margin requirements and haircuts, forcing certain leveraged players to raise more cash. Dealers’ balance sheets become more expensive to use, and at the same time, high-yielding Treasuries become an increasingly powerful competitor to private credit, equities, real estate, and industrial investments.
Rising rates therefore act as a liquidity vacuum. Not because money is disappearing, but because rising rates reduce the value of certain assets, increase the amount of capital needed to hold the same positions, and simultaneously offer a much higher return on risk-free assets.
We can therefore observe a seemingly paradoxical situation: the Fed is adding monetary liquidity while the bond market is withdrawing balance sheet liquidity.
The Treasury must always find its marginal buyer
This contradiction becomes even more significant when we consider the U.S. government’s financing needs. Banks, money market funds, hedge funds, insurers, pension funds, and foreign investors must absorb a considerable amount of securities.
This debt naturally ends up finding buyers. But when demand is insufficient at the offered terms, the adjustment mechanism is simple: the yield must rise.
An auction can therefore be fully subscribed while still constituting bad news for financial conditions. The problem is not necessarily that the Treasury can no longer find buyers. It is a matter of at what yield it must find them.
This is where a potentially self-reinforcing cycle emerges:
rising long-term rates → falling bond prices → valuation losses → weaker balance-sheet capacity → lower marginal demand → higher yields required to absorb the next issuance → even higher rates.
Added to this is the gradually increasing budgetary cost. The more U.S. debt is refinanced at high rates, the more interest payments rise; the more interest payments rise, the harder it is to reduce deficits; the longer deficits remain high, the more the Treasury must issue.
Rising rates can thus end up creating part of the future bond supply that fuels its own rise.
It is precisely to prevent this mechanism from spiraling out of control that maintaining ample reserves becomes so important for the Fed.
Why today’s world is different from that of 2008
When the Fed launched its first massive asset-purchase programs after the financial crisis, many predicted a surge in inflation. That is not what happened.
Part of the explanation obviously lies in the very nature of QE: the reserves created by the Fed are not directly injected into consumers’ pockets. Instead, they first alter the balance sheets of the financial system, help drive down yields, and fuel rising asset prices.
But there was a second reason, probably just as important. After 2008, the United States was grappling with high unemployment, underutilized industrial capacity, and depressed private demand. Globalization made it possible to increase production through Asian supply chains, energy was abundant, and the shale oil and gas revolution was set to further increase available capacity.
When monetary conditions favored a recovery in demand, the global economy therefore had significant capacity to meet that demand by producing more. Part of the increase in nominal demand could thus be transformed into real growth rather than inflation.
Today’s world is very different.
Let’s imagine a company that needed $100 to produce 100 units. Under the old system, more favorable financial conditions might have allowed it to obtain $120, invest that money, and produce 120 units.
Now imagine that same company facing a sharp rise in the prices of gasoline, diesel, electricity, and transportation. It may now need $120 just to continue producing its 100 units.
That is the difference.
When supply can no longer keep pace, more money does not necessarily finance more production. It may simply make it possible to finance the same volume of activity at higher prices.
The problem, then, is not that QE has mysteriously changed in nature. It is the world in which QE operates that has changed.
When the system resists demand destruction
An oil shock typically contains its own corrective mechanism. When energy prices rise sharply, households spend an increasing share of their income on gasoline, heating, or electricity and have less money left over for other expenses. At the same time, businesses see their costs rise. Margins shrink, investment slows, and then hiring slows as well.
Rising energy prices are therefore initially inflationary, but they normally end up reducing demand enough to slow the economy and, ultimately, ease inflationary pressures.
And this is precisely where fiscal policy and monetary policy begin to converge.
The U.S. government continues to run substantial deficits, which maintain a high level of spending in the economy. At the same time, by ensuring that sufficient reserves remain in the banking system and by intervening in the T-Bill market to prevent the Treasury’s financing needs from causing an excessive contraction in liquidity, the Fed mitigates some of the financial tightening.
By preventing rising interest rates from causing genuine systemic stress, the Fed also mitigates some of the destruction of demand that the energy shock would normally cause.
Quantitative easing (QE) obviously does not directly drive up oil prices, and bank reserves are not used to buy barrels of oil. But if monetary policy prevents financial conditions from tightening as much as they otherwise would, it helps sustain nominal demand that would normally have slowed further.
In the 2010s, this additional liquidity encountered significant spare capacity and a highly elastic global supply. Today, it may face an economy already constrained by energy, refining capacity, electrical infrastructure, or certain essential components.
How, then, can we maintain sufficient liquidity to finance the Treasury and the economy without simultaneously fueling inflation caused by these supply constraints?
This is where artificial intelligence comes into our story.
AI as a productivity bet
The U.S. economy needs real growth. It needs it because its debt is rising, because its deficits remain substantial, and because a system that requires ever-increasing amounts of liquidity becomes extremely difficult to stabilize if the quantity of goods and services produced does not grow fast enough.
The least painful way to solve this equation would be a dramatic acceleration in productivity.
And that is exactly what AI promises.
The current boom is no longer limited to a few extravagant valuations on the Nasdaq. It is driving a genuine investment cycle: data centers, semiconductors, electrical infrastructure, networks, and equipment. These hundreds of billions of dollars in CAPEX are justified by the promise that, once widespread throughout the economy, artificial intelligence will enable greater output from available resources.
An economy capable of producing 120 where it previously produced only 100 can obviously absorb an increase in nominal demand much more easily than an economy stuck at 100. Faster productivity growth also increases real GDP, incomes, and tax revenues, thereby making the debt burden more bearable.
This is where Bessent’s bet becomes particularly interesting. The point is not to claim that the Treasury or the Fed are deliberately fueling an AI bubble; there is no evidence to support such an intention. But the success of the productivity boom promised by AI would, in fact, help resolve the problem facing U.S. authorities.
The system needs liquidity to finance its debt and investments. This liquidity risks becoming inflationary if physical capacity grows too slowly. Productivity must therefore be increased. But to achieve these productivity gains, one must first finance the massive investment cycle intended to produce them.
It is this cycle that is beginning to resemble a veritable headlong rush.
A race against time
The problem is that AI-related spending is occurring now, while productivity gains will not materialize until later and remain difficult to measure. During this interim period, the technology boom may even exacerbate tensions by sustaining substantial demand for capital, energy, construction, and equipment — at the very moment when consumers are beginning to feel the effects of the energy shock.
This is what makes the observation published this week by Blacklion particularly interesting. While some measures of inflation expectations are beginning to reflect the destruction of demand caused by the oil shock, the SOFR curve and OIS rates are not reacting as one might expect in a classic economic slowdown scenario:

The curve steepens until around the fall of 2027. There are, of course, several possible explanations, and it would be an overstatement to attribute this trend solely to AI. But the hypothesis is worth considering: the massive cycle of technology CAPEX could sustain enough investment demand to prevent the U.S. economy from slowing down as rapidly as it normally would following an oil shock of this magnitude.
Consumer spending is slowing because energy costs are eroding purchasing power, while technology companies continue to invest hundreds of billions of dollars, the government maintains massive deficits, and the Treasury continuously refinances a growing debt. Traditional private demand can therefore slow without aggregate nominal demand actually collapsing.
The entire equation then depends on time.
If productivity gains materialize quickly enough, more money and credit will flow into an economy capable of producing more. The United States will then have used the current abundance of capital to finance the real growth that will, in the future, make debt and deficits more sustainable.
But if these gains come too late, or if they are smaller than hoped for, the equation becomes much more difficult. The United States will end up with more public debt, more private liabilities tied to the investment cycle, and an economy still facing the same physical constraints.
The Fed will then have to choose between allowing financial conditions to tighten enough to bring about the reduction in demand needed to bring inflation back to its target, or continuing to provide liquidity to a system that keeps demanding more and more.
In the first scenario, tighter financial conditions would eventually weigh heavily on valuations, real estate, credit, indebted companies, and the Treasury’s own cost of borrowing. In the second, ever-larger monetary interventions could gradually shift the problem from the bond market to the currency and inflation.
The problem doesn’t go away — it simply shifts to another place.
And there is one final risk: the very engine meant to solve the problem may itself fall victim to this tightening. The high valuations of AI-related companies currently make it easier for them to finance their investments. But if investors begin to doubt the economic return on these hundreds of billions of dollars in CAPEX, valuations could fall precisely at a time when financing needs remain enormous. Some projects would then be postponed, investment would slow, and the boom that was supposed to generate future productivity gains would itself begin to run out of steam.
That is why the Fed is unlikely to run out of dollars. The real risk is that the real economy will not produce fast enough what all those dollars will need to buy.
The bet behind the artificial intelligence boom therefore goes far beyond technology: the United States is betting that productivity will rise quickly enough for real growth to catch up with the growth in debt and liquidity needed to finance it.
And what about gold in all of this?
This brings us back to the volatility of the gold price mentioned at the beginning of this article. This volatility does not necessarily reflect a market that is constantly changing its view on inflation or monetary policy. Rather, it reflects the balance of power between the two mechanisms we just described: on one hand, a Fed that provides the reserves needed to keep the system liquid; on the other, a bond market where rising yields are gradually draining financial capacity from the rest of the system.

That is why a decline in long-term rates can trigger an extremely rapid rise in gold prices, while a new surge in yields almost immediately produces the opposite effect. The fundamental thesis does not change several times a week: it is the balance of power between the two drivers of liquidity that shifts.
The real question, therefore, is not whether the Fed can still create reserves. It can. The question is how much it will have to create to prevent rising long-term rates from triggering a systemic tightening, and how far it can go without fueling the very inflation it is trying to control.
This is what makes the current situation particularly unstable. As long as T-bill purchases and the abundance of reserves offset the liquidity drain caused by the bond market, the system can continue to function under relatively favorable financial conditions. But if long-term rates rise fast enough to gain the upper hand, the contraction in liquidity could become much more severe.
Conversely, if this pressure ultimately forces the Fed to intervene further, the market will then have to ask itself whether the support needed for the financial system is becoming incompatible with the fight against inflation.
Gold finds itself right in the middle of this contradiction. That is likely why it is so volatile and so interesting to watch right now.
Reproduction, in whole or in part, is authorized as long as it includes all the text hyperlinks and a link back to the original source.
The information contained in this article is for information purposes only and does not constitute investment advice or a recommendation to buy or sell.


Leave a comment