Key Takeaways
- Financial assets include cash, stocks, bonds, and bank deposits.
- They derive value from contracts or ownership claims.
- Unlike physical assets, they don’t have inherent tangible worth.
- Their value is affected by market supply and demand.
- Financial assets carry varying degrees of risk.
What Is a Financial Asset?
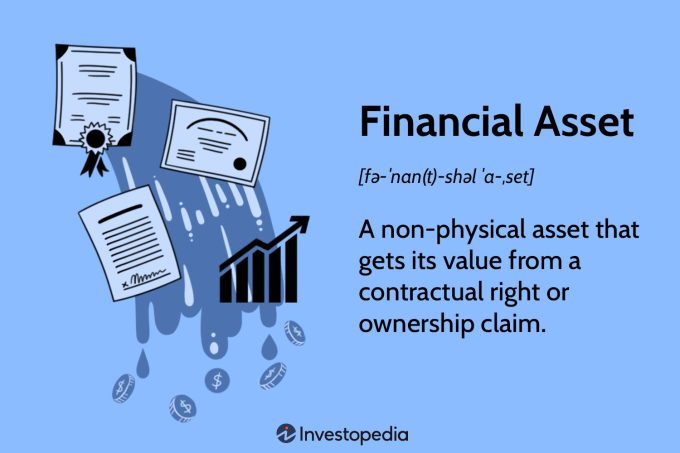
A financial asset is a liquid asset that gets its value from a contractual right or ownership claim. Cash, stocks, bonds, mutual funds, and bank deposits are all are examples of financial assets. Unlike land, property, commodities, or other tangible physical assets, financial assets do not necessarily have inherent physical worth or even a physical form. Rather, their value reflects factors of supply and demand in the marketplace in which they trade, as well as the degree of risk they carry.
Investopedia / Mira Norian
Understanding Financial Assets
Assets can be real, financial, or intangible. Real assets are physical, drawing value from substances or properties like precious metals, land, real estate, and commodities like soybeans, wheat, and oil. Intangible assets are valuable but can’t be touched. They include patents, trademarks, and intellectual property.
Financial assets fall between these two classes. They may seem intangible with only the stated value on a piece of paper, such as a dollar bill or a listing on a computer screen. What that paper or listing represents, though, is a claim of ownership of an entity, like a public company, or contractual rights to payments—say, the interest income from a bond. Financial assets derive their value from a contractual claim on an underlying asset.
This underlying asset may be either real or intangible. For instance, commodities are the underlying assets pinned to such assets as futures contracts or some exchange-traded funds (ETFs). Likewise, real estate is the real asset associated with shares of real estate investment trusts (REITs). REITs are financial assets and are publicly traded entities that own a portfolio of properties.
The Internal Revenue Service (IRS) requires businesses to report financial and real assets together as tangible assets for tax purposes. The grouping of tangible assets is separate from intangible assets.
Common Types of Financial Assets
According to the commonly cited definition from the International Financial Reporting Standards (IFRS), financial assets include:
- Cash
- Equity instruments of an entity, such as a share certificate
- A contractual right to receive a financial asset from another entity—known as a receivable
- The contractual right to exchange financial assets or liabilities with another entity under favorable conditions
- A contract that will settle in an entity’s own equity instruments
In addition to stocks and receivables, the above definition comprises financial derivatives, bonds, money market or other account holdings, and equity stakes. Many of these financial assets do not have a set monetary value until they are converted into cash, especially in the case of stocks where their value and price fluctuate.
Aside from cash, the more common types of financial assets that investors encounter include:
- Stocks: These assets have no set expiration date. Investors who buy stocks become part owners of a company and share in its profits and losses. They may be held indefinitely or sold to others.
- Bonds: These assets allow companies or governments to finance short-term projects. Bondholders are lenders, the bonds state how much money is owed, the interest rate being paid, and the bond’s maturity date.
- Certificates of deposit (CDs): These assets allow an investor to deposit an amount of money at a bank for a specified period with a guaranteed interest rate. A CD pays monthly interest and can typically be held between three months to five years depending on the contract.
Pros and Cons of Highly Liquid Financial Assets
The purest form of financial assets is cash and cash equivalents—checking accounts, savings accounts, and money market accounts. Liquid accounts are easily turned into funds for paying bills and covering financial emergencies or pressing demands.
Other varieties of financial assets might not be as liquid. Liquidity is the ability to change a financial asset into cash quickly. For stocks, an investor can buy or sell holdings from a ready market. Liquid markets are those where there are plenty of buyers and plenty of sellers and no extended lag time in trying to execute a trade.
In the case of equities like stocks and bonds, an investor has to sell and wait for the settlement date to receive their money—usually one business day.
Maintaining funds in liquid financial assets can result in greater preservation of capital. Money in bank checking, savings, and CD accounts are insured against loss of up to $250,000 by the Federal Deposit Insurance Corporation (FDIC) and the National Credit Union Association (NCUA) for credit unions. If the bank fails, your account has coverage up to $250,000. However, since each financial institution is covered individually, an investor with brokered CDs totaling over $250,000 in one bank faces losses if the bank becomes insolvent.
Liquid assets like checking and savings accounts have a limited return on investment (ROI) capability. ROI is the profit you receive from an asset divided by the cost of owning that asset. They may provide modest interest income but, unlike equities, they offer little appreciation. CDs and money market accounts also restrict withdrawals for months or years. When interest rates fall, callable CDs are often called, and investors end up moving their money to potentially lower-income investments.
Pros
-
Liquid financial assets convert into cash easily
-
Some financial assets have the ability to appreciate in value
-
FDIC and NCUA insure accounts up to $250,000
Cons
-
Highly liquid financial assets have little appreciation
-
Illiquid financial assets may be hard to convert to cash
-
The value of a financial asset is only as strong as the underlying entity
What Is an Illiquid Asset?
The opposite of a liquid asset is an illiquid asset. Real estate and fine antiques are examples of illiquid financial assets. These items have value but cannot convert into cash quickly.
Another example of an illiquid financial asset are stocks that do not have a high volume of trading on the markets. Often these are investments like penny stocks or high-yield, speculative investments where there may not be a ready buyer when you are ready to sell.
Keeping too much money tied up in illiquid investments has drawbacks—even in ordinary situations. Doing so may result in an individual using a high-interest credit card to cover bills, increasing debt and negatively affecting retirement and other investment goals.
Real-World Example of Financial Assets
Businesses, as well as individuals, hold financial assets. In the case of an investment or asset management company, the financial assets include the money handled for clients, which is called assets under management (AUM). For example, BlackRock was the largest investment manager in the world with $11.6 trillion in AUM as of Dec. 31, 2024.
In the case of banks, financial assets include the worth of the outstanding loans it has made to customers. Capital One, the ninth-largest bank in the U.S., reported over $490 million in total assets as of March 31, 2025.
Is a 401(k) a Liquid or an Illiquid Asset?
This depends. Retirement accounts like 401(k)s are generally considered illiquid assets because they are difficult to convert to cash quickly without incurring a significant loss, especially before you turn 59½. They do, however, become more liquid after you turn 59½ because you are able to make withdrawals without being penalized.
Is My Car a Liquid Asset?
Your car isn’t necessarily considered a liquid asset. That’s because it may take you some time to sell it, and you may not get the same price that you paid for it. You may also incur additional costs to sell your vehicle, including advertising, costs to repair, and other potential fees.
What Are the Ownership Rights of Financial Assets?
Certain assets come with specific ownership rights. For instance, checking and savings accounts allow you to make deposits, withdrawals, and transfers among other transactions. Stock ownership may give the shareholder voting rights and the right to receive dividends while bond ownership allow the holder to receive interest payments and their principal investment when the bond matures.
The Bottom Line
A financial asset is anything you own that has a value that is derived from a claim of ownership. This value reflects any associated risks along with supply and demand in the market. They are contrasted with liabilities, which refer to money that you owe. Financial assets support economic growth and the creation of wealth and also help individuals achieve and preserve their financial goals.


Leave a comment