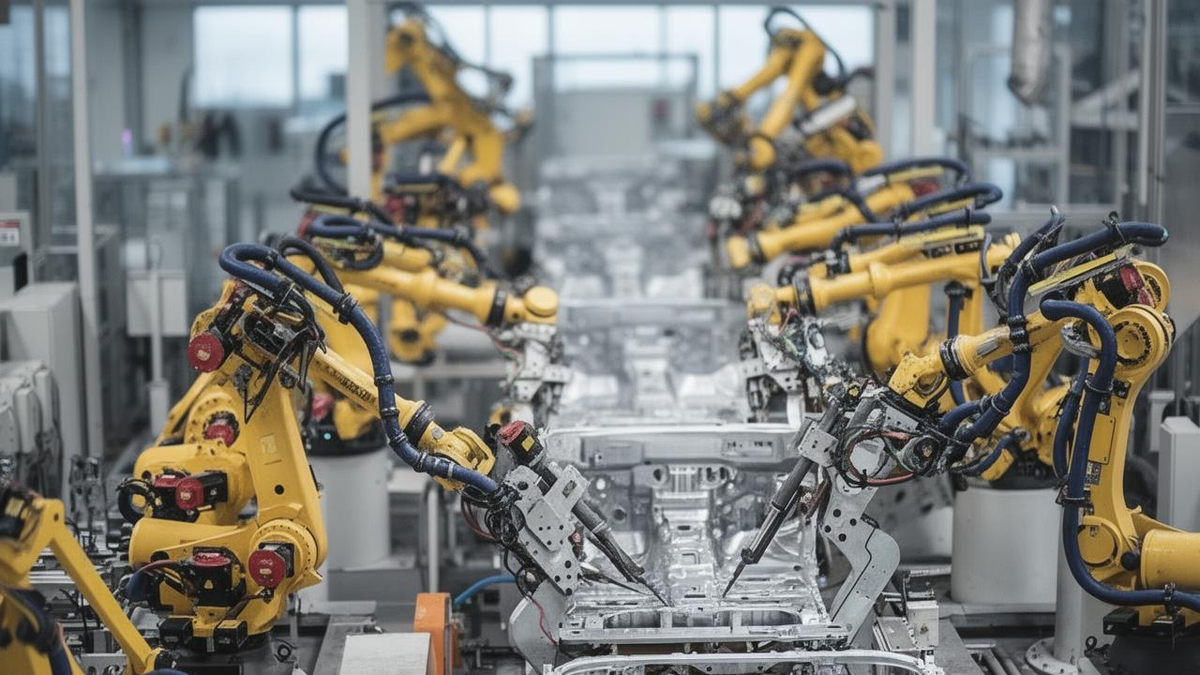
Beneath the surface of declining overall growth, China’s fixed-asset investment is undergoing a profound structural transformation. Wang Guanhua, spokesperson for the National Bureau of Statistics and deputy director of the Department of Comprehensive Statistics of the National Economy, said at a State Council Information Office press conference on September 15 that nationwide fixed-asset investment fell 7.2% year-on-year in the first eight months of the year, but total investment still approached 30 trillion yuan, with investment structure and quality continuing to improve and new-growth-driver sectors expanding against the trend.
Wang noted that the slowdown in investment growth resulted from a combination of factors. On one hand, frequent extreme weather events—including summer heatwaves, typhoons, and flooding—adversely affected project construction in some regions. On the other hand, the external environment remained complex and volatile, with growing uncertainties and unpredictable factors, while the domestic economy was still in the process of transitioning between old and new growth drivers, making corporate investment decisions more cautious.
By sector, infrastructure investment fell 4.0% year-on-year, manufacturing investment declined 2.3%, and real estate development investment dropped 19.9%. Private investment decreased 10.1%, but excluding real estate development, the decline narrowed to 6.4%.
“As the economy transitions to a new stage of development, we cannot simply judge the effectiveness of investment by growth rates alone,” Wang emphasized. “Whether it constitutes effective investment, whether it is directed toward transformation and upgrading, and whether it can build momentum for long-term economic development—these dimensions deserve greater attention.”
Intellectual Property and High-Tech Investment Accelerate
Despite overall growth pressure, the intrinsic quality of investment is improving. In the first eight months, intellectual property product investment grew 9.2% year-on-year, accounting for 15.2% of total investment, with its share up 2.3 percentage points from a year earlier. Within this category, investment in computer software and databases rose 10.9%, and research and development investment grew 7.8%, together accounting for more than 95% of intellectual property product investment.
Wang described such spending as “energy-storing” investment. He said the main outputs of intellectual property product investment are knowledge-based assets such as technologies, software, and databases, which can both promote the commercialization of scientific and technological achievements and effectively empower industrial transformation and upgrading, improving production efficiency—an investment that benefits both the present and the long term.
High-tech industry investment also performed impressively. It grew 5.2% year-on-year in the first eight months, with the cumulative growth rate accelerating for three consecutive months, up 0.2 percentage points from the January-July period. Rapid growth in core AI technologies and application demand drove investment in electronic specialty materials manufacturing and integrated circuit manufacturing up 8.5% and 12.0%, respectively. The development of the new energy vehicle industry, combined with strong energy storage market demand, pushed lithium-ion battery manufacturing investment up 20.6%.
The shift in capital flows is more clearly visible in the detailed data:
| Investment Sector | Jan-Aug YoY Growth |
|---|---|
| Overall fixed-asset investment | -7.2% |
| Infrastructure investment | -4.0% |
| Manufacturing investment | -2.3% |
| Real estate development investment | -19.9% |
| Private investment | -10.1% |
| High-tech industry investment | +5.2% |
| Intellectual property product investment | +9.2% |
| Lithium-ion battery manufacturing investment | +20.6% |
| Integrated circuit manufacturing investment | +12.0% |
| Internet and related services investment | +42.0% |
Note: Data sourced from the National Bureau of Statistics macroeconomic data released on September 15.
“Six Networks” Construction and Policy Reinforcement
Modern infrastructure has become another key focus of investment. In the first eight months, investment in internet and related services tied to the “Six Networks” initiative grew 42% year-on-year, while air transport and water transport investment rose 16.7% and 14.7%, respectively, and power supply investment increased 12.7%. As of end-June, China had built more than 70 major computing power corridors around its computing hub network.
This year marks the opening year of the “15th Five-Year Plan,” with a batch of major engineering projects commencing construction in succession. Cross-regional transport corridors, major energy and water conservancy projects, new infrastructure, and urban renewal projects are all advancing in an orderly manner. Wang said central budget investment has been largely disbursed, the pace of local government special bond issuance and utilization has accelerated, and funds from new-type policy financial instruments will be deployed promptly, with coordinated policy efforts expected to further stimulate and unleash investment potential.
Facing persistent investment decline, policy measures are being intensified. According to a report by Yicai, over the past month, China’s National Development and Reform Commission has convened multiple coordination meetings on “Six Networks” major projects, “Two Priorities” construction promotion meetings, a national investment work conference, and a meeting on advancing major projects under the 15th Five-Year Plan outline, all aimed at getting new projects started as early as possible and stabilizing investment.
Activating private investment has also been put on the agenda. The NDRC’s Private Economy Bureau recently held a symposium with private enterprises and industry associations, centrally promoting a batch of investment projects across four key areas—transportation, logistics, water conservancy, and energy—totaling 36 projects with an estimated total investment of 61.4 billion yuan (approximately $9.2 billion), of which 15.6 billion yuan (approximately $2.3 billion) is intended to attract private capital. Project types include railways, warehousing, wind power, energy storage, charging facilities, and water diversion works.
Wang Qing, chief macro analyst at Golden Credit Rating, believes that as fiscal spending and the use of various government bond funds accelerate—particularly with the full implementation of the 800 billion yuan (approximately $119.2 billion) new-type policy financial instrument—the pace of “Six Networks” and major project construction is expected to quicken, and infrastructure investment growth will turn positive in the latter part of the year. He judges that this will become the primary manifestation of “strengthening counter-cyclical adjustment” and the main driver for stabilizing investment this year.
Looking at the overall data, Chinese investment is shifting from a past emphasis on scale expansion toward a greater focus on technological innovation, industrial upgrading, and foundational support. Wang concluded that the investment structure is showing a trend toward innovation and quality, with investment quality and efficiency continuously improving—an optimization of capital allocation that is precisely what high-quality development requires and expects.


Leave a comment