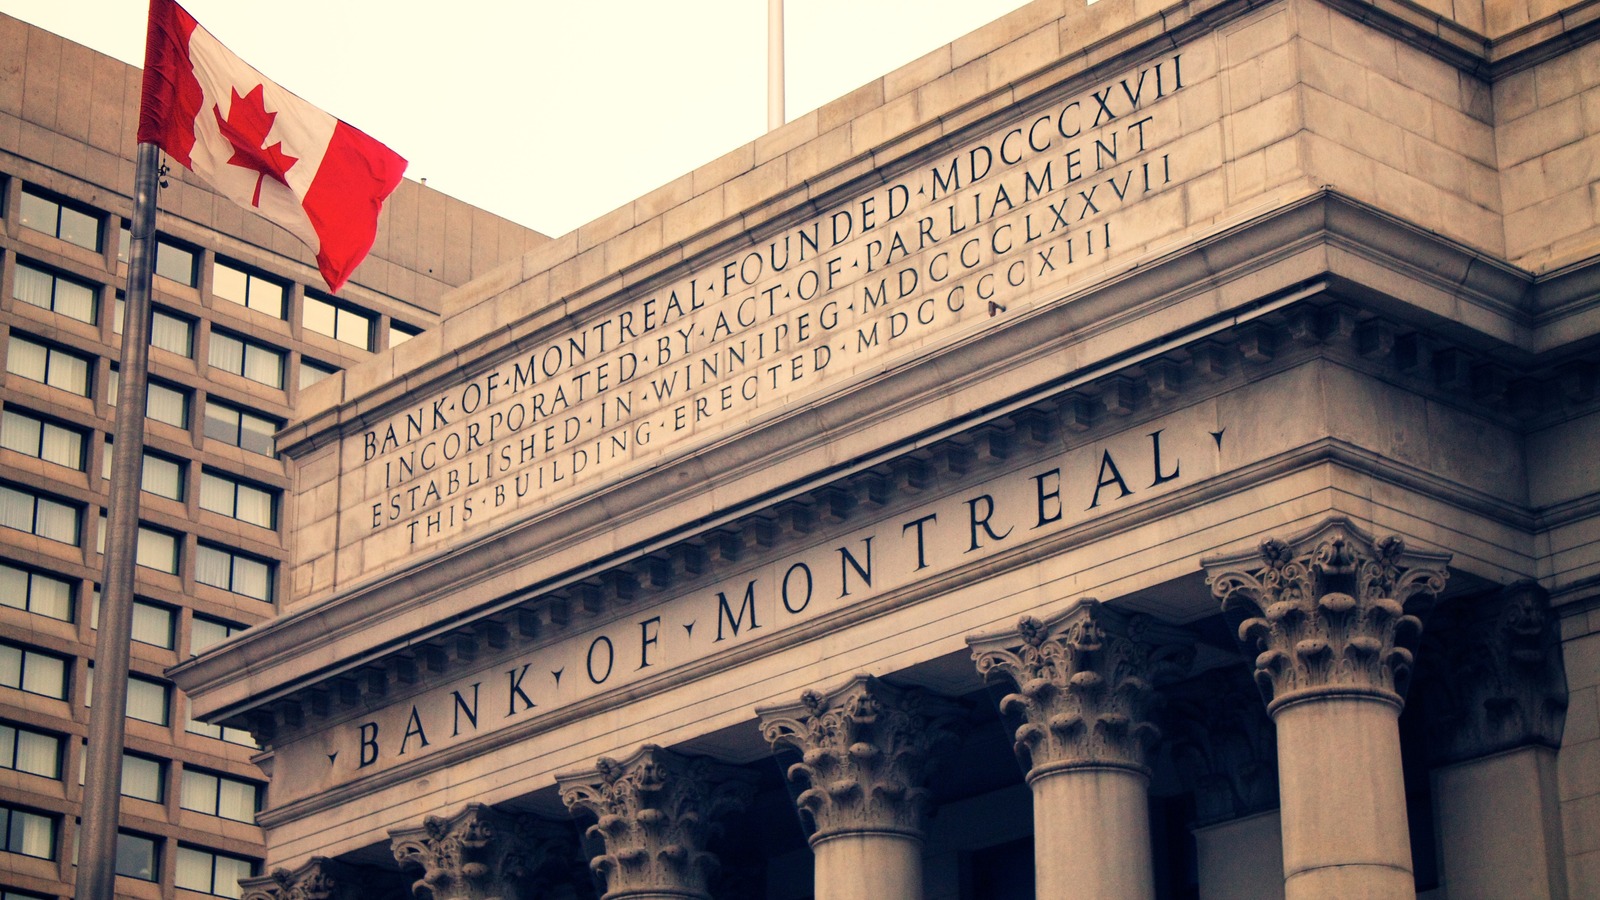
Bank of Montreal has delivered a powerful 5 year run, and with fresh capital commitments and balance sheet moves in the spotlight, investors are asking whether that share price now lines up with the returns the bank earns on its own capital.
- The stock has returned 136.1% over 5 years, which puts real pressure on the question of whether the underlying return on capital can support that kind of compounding.
- BMO’s plan to mobilize up to $70b toward critical Canadian sectors and AI related projects may support future earnings power, but it could also reshape how efficiently the bank deploys each new dollar of capital.
- If you’d rather focus on earnings, this one’s for you. See why Bank of Montreal’s 19.3x P/E tells a different valuation story.
The issue now is whether Bank of Montreal’s current price is justified by the returns it produces on the capital it invests and retains inside the business.
If you are weighing whether Bank of Montreal’s 5 year, 136.1% return still lines up with the returns it earns on its capital, it can help to compare that question against 4 high quality undervalued stocks.
Does Bank of Montreal Look Undervalued on Excess Returns?
The Excess Returns framework looks at how profitably Bank of Montreal can reinvest shareholders’ equity above its own cost of capital. For BMO, the model leans on an average return on equity of 13.70% and a stable earnings power of about CA$16.27 per share, against a stable book value base of roughly CA$118.74 to CA$121.89 per share, both drawn from analyst estimates. That return profile sits above the modelled cost of equity of CA$8.50 per share, leaving an excess return of CA$7.77 per share that compounds as retained earnings grow.
The dividend discount cross check, which assumes a payout ratio of 53.64% and dividend per share of CA$7.06 growing at 3.08%, also finds value support that sits meaningfully above the current CA$241.64 share price. BMO’s plan to mobilize up to CA$70b toward critical Canadian sectors and AI projects helps explain why the model still assigns value to future reinvestment capacity despite the heavy capital commitments. If you want to see how those inputs translate into a single intrinsic value estimate compared to the current market price, you can review the detailed Excess Returns output beside other approaches in. Find out what Bank of Montreal could be worth using our Excess Returns estimate.
The Bank of Montreal Narrative: What Would Justify Today’s Price?
Simply Wall St Narratives for Bank of Montreal pick up where the valuation puzzle leaves off. They spell out which future paths for Bank of Montreal’s growth, margins and earnings would need to play out for the shares to end up worth significantly more or less than today. Rather than focusing on a single multiple or model output, each Narrative lays out the assumptions behind its own fair value view so you can compare those expectations with actual results as they come through. Narratives live on Simply Wall St’s Community page and are designed to sit alongside your own judgment, not replace it.
One of the top community narratives on Bank of Montreal: 5% undervalued
“BMO’s continued investment in digital and AI-powered banking platforms, such as the LUMI Assistant and multiple award-winning payment innovations, is improving operational efficiency and customer engagement…”
Discover why this Narrative puts Bank of Montreal at 5% undervalued.
Before you decide on Bank of Montreal, there is one more piece to check
Valuation only tells part of the story for Bank of Montreal, because Simply Wall St’s broader review has also flagged specific concerns that could change how you frame the opportunity. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Bank of Montreal might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com


Leave a comment