Key Takeaways
- CFAT measures a company’s cash-generating ability after taxes.
- Depreciation and amortization are added back to net income in CFAT.
- CFAT helps assess a company’s financial health over time.
- Compare CFAT within the same industry for accuracy.
- High CFAT indicates good capacity for cash obligations and growth.
What Is Cash Flow After Taxes (CFAT)?
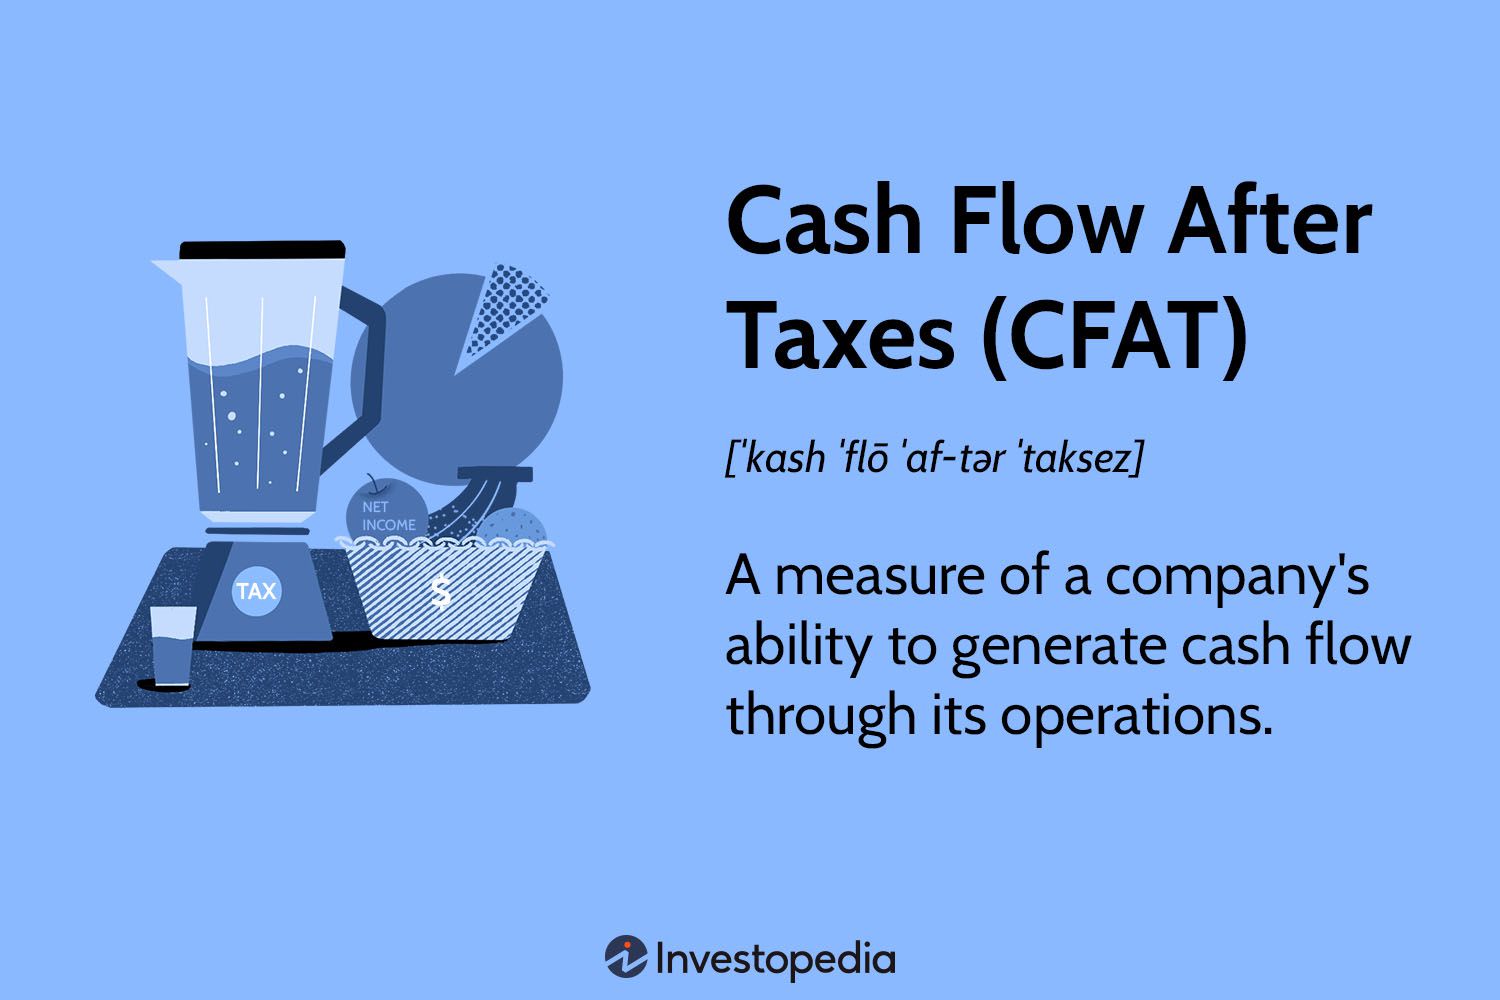
Cash flow after taxes (CFAT) is an important measure of a company’s cash-generating ability and overall financial health, showing how much cash a business produces from its operations after taxes.
It is calculated by adding non-cash charges, such as amortization, depreciation, restructuring costs, and impairments, back to net income. Investors and analysts use CFAT to evaluate a company’s ability to support growth, fund investments, meet financial obligations, and compare financial performance with competitors in the same industry.
CFAT and Company Financial Health
CFAT is a measure of cash flow that takes into account the impact of taxes on profits. It can be used to determine the cash flow of an investment, a project, or an entire company.
To calculate after-tax cash flow, you must add depreciation, amortization, and other non-cash charges back to net income. Depreciation is a non-cash expense that represents the declining economic value of a physical asset, such as a piece of machinery or a fleet of trucks, but is not an actual cash outflow. Amortization is much like depreciation but for intangible assets, such as copyrights or trademarks. (Depreciation and amortization are both subtracted as expenses to calculate net profits. In calculating CFAT, they are added back in.)
Many investors consider cash flow to be a more reliable and trustworthy measure of a company’s financial health than profits. That’s because non-cash expenses, such as depreciation, are more easily manipulated through “creative accounting” to make a company appear profitable, at least on paper.
How to Calculate CFAT
Here is the formula for calculating CFAT:
CFAT=net income+d+a+onccwhere:d=Depreciationa=Amortizationoncc=Other non-cash charges
For example, let’s assume a project with an operating income of $2 million has a depreciation value of $180,000 and no amortization. The company pays a combined federal and state tax rate of 25%. The net income generated by the project can be calculated as:
Earnings before tax (EBT) = $2 million – $180,000
EBT = $1,820,000
Net income = $1,820,000 – (25% x $1,820,000)
Net income = $1,820,000 – $455,000
Net income = $1,365,000
CFAT = $1,365,000 + $180,000
CFAT = $1,545,000
Depreciation is an expense that acts as a tax shield. However, as it is not an actual cash flow, it must be added back to the after-tax income to produce a more accurate picture of cash flow.
Investor Insights From CFAT
The present value of cash flow after taxes can be calculated to decide whether or not an investment in a business is worthwhile. CFAT is important for stock investors and analysts because it gauges a corporation’s ability to meet its cash obligations, such as an increase in working capital and payroll to support growth, make cash investments in fixed assets, or eventually and in the long run, issue cash dividends or distributions. The higher the CFAT, the better positioned a business is to make distributions to investors.
CFAT can also be used as a measure of a company’s financial health and performance over time and in comparison to competitors within the same industry. Different industries have different levels of capital intensity and thus different levels of depreciation. While cash flow after taxes is a good way to determine whether a business is generating positive cash flows after the effects of income taxes have been taken into consideration, it does not account for cash expenditures used to acquire fixed assets, which will vary among industries.
What Is Free Cash Flow?
Free cash flow is a measure of the cash that a company generates after accounting for cash outflows to support its operations and any capital expenditures—in other words, the money that is left over after it has covered all of its expenses. Unlike net income it doesn’t include non-cash charges.
What Is Operating Cash Flow?
Operating cash flow refers to the cash generated by a company as a result of its normal business activities, such as an automaker’s production of cars. It does not include any cash produced by its investments or other financial activities. Operating cash flow is used by investors as an indicator of whether a company is producing enough in profits through its everyday operations to cover its liabilities.
What Is a Non-Cash Charge?
A non-cash charge is an accounting term for expenses that a company is able to write down on its balance sheet but that do not involve an actual cash outflow. Examples of non-cash charges include depreciation, amortization, depletion, stock-based compensation, and asset impairments.
Depreciation and amortization are accounting practices that allow a company to write down the value of its tangible and intangible assets, respectively, over their useful life. Depletion, which is most common in the energy and raw materials industries, allocates the cost of extracting natural resources, such as oil or minerals, from the earth. Stock-based compensation refers to the payment of employees, typically executives, through non-cash means, such as shares of stock or stock options in that company. Asset impairment refers to assets that have declined in value beyond their normal depreciated value on the company’s balance sheet, such as a piece of machinery suddenly made obsolete by new technology or changing demand on the part of consumers.
The Bottom Line
Cash flow after taxes (CFAT) can be a useful measure of a company’s financial health and its ability to generate sufficient cash to meet its (and its investors’) needs. In comparing CFAT among different companies, it is important to recognize that cash needs can vary widely from one industry to another, so it’s best to compare companies in the same or very similar industries.


Leave a comment