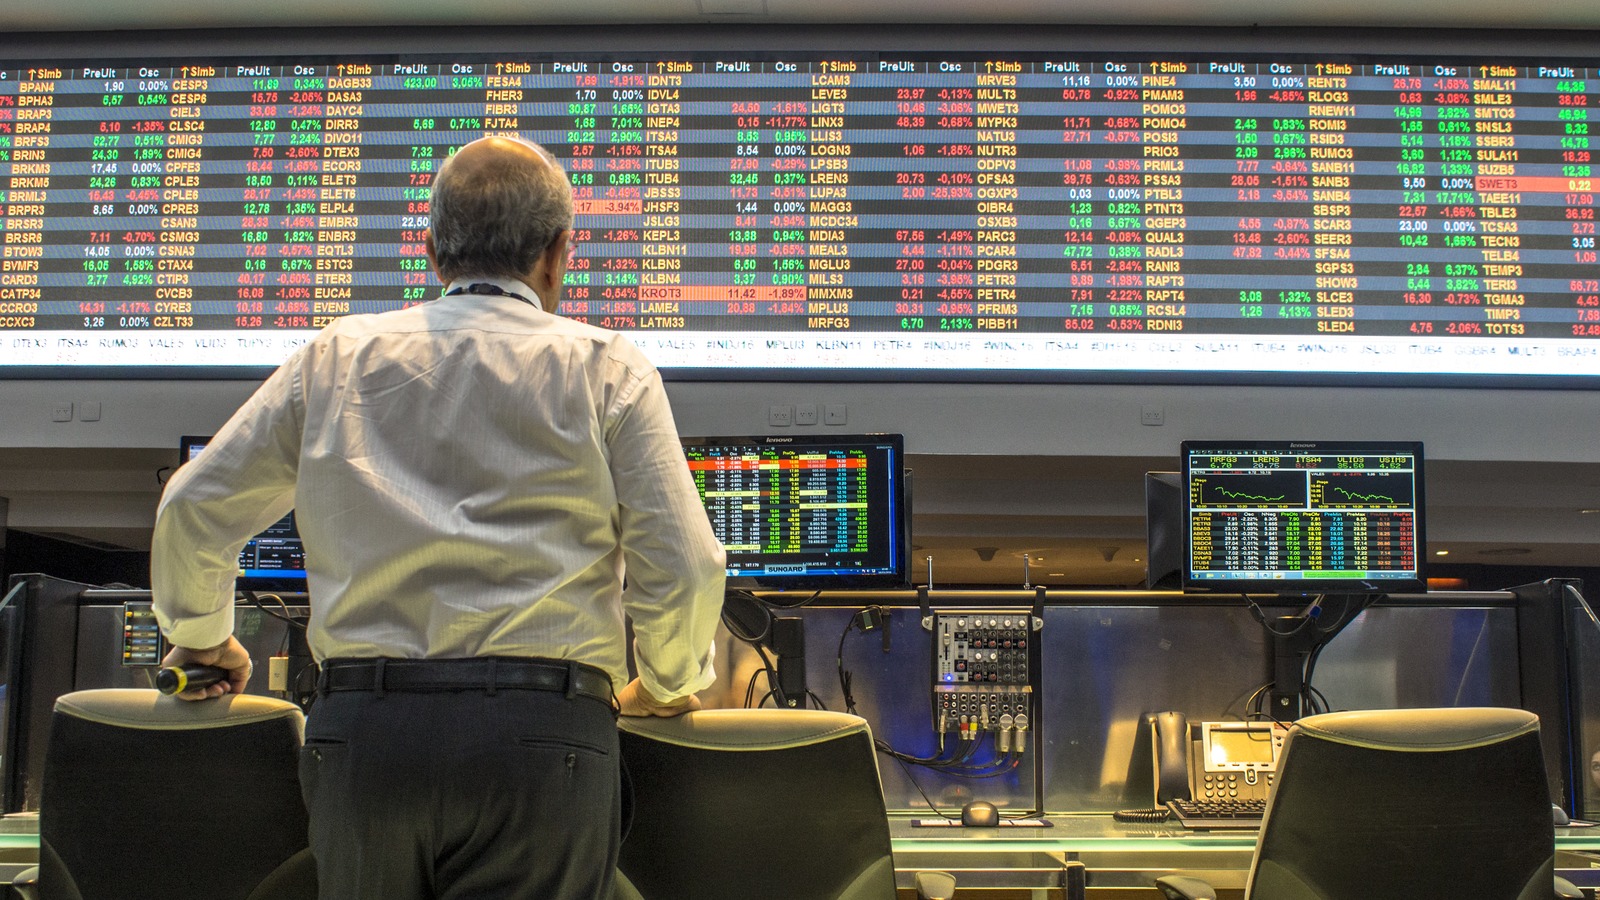
Nasdaq (NDAQ) is pushing deeper into tokenization, extended trading hours and institutional data products, with plans for Equity Tokens in 2027 and fresh tools like Juniper Square’s Capital Intelligence for capital-raising workflows.
Recent announcements around 23/5 trading and Equity Tokens come as Nasdaq’s share price has slipped about 6% over the past month after a 19% gain over 90 days, while total shareholder return of 8% over one year and roughly 100% over three years points to longer term momentum remaining intact.
Scan beyond Nasdaq and size up other market-infrastructure and data-heavy plays with the curated list of 87 AI infrastructure stocks that could benefit as trading and tokenization technology scales.
Nasdaq’s recent pullback after a strong three year run can look like routine sentiment cooling, or an early signal that expectations ran ahead of the business. Which version does the current valuation reflect?
Most Popular Narrative: 10.2% Undervalued
Nasdaq last closed at $93.55, while the most followed narrative pegs fair value closer to $104.19. This suggests investors are weighing a business with expanding margins and steady growth against a stock that has already delivered strong multi year returns.
Four crashes, four different causes, four different recovery timelines, two years, fifteen years, years, months. If there were a reliable way to know in real time which kind you were in, that would be worth more than almost anything else in investing. Nobody has reliably had that in any of these four cases. What every one of them rewarded instead was the boring stuff, not being leveraged past what you could survive, having a plan for how much you were willing to lose before you needed to act on it, and not needing to guess correctly about the recovery shape to avoid being wiped out waiting for it.
See why 5 investors see Nasdaq as 10% undervalued.
Result: Fair Value of $104.19 (UNDERVALUED)
Still, that 23/5 trading push and the equity token story could disappoint if regulatory approvals move slowly, or if institutional demand for new formats underwhelms expectations.
Find out about the key risks to this Nasdaq narrative.
Another View: What Nasdaq’s P/E Is Saying
The fair value narrative for Nasdaq points to upside, but the earnings multiple paints a more mixed picture. The stock trades on a P/E of 26.6x versus a peer average of 25x, and against a fair ratio of 16.4x that the market could drift toward. That spread can look like a quality premium or a valuation risk. Which story do you think fits best?
See what the numbers say about this price in our valuation breakdown, starting with the detailed comparison to the sector and the fair ratio methodology, in See what the numbers say about this price — find out in our valuation breakdown.

Next Steps
Mixed signals on Nasdaq can pull you in both directions, so treat this as your cue to move quickly and verify the data yourself. To weigh the upside against the concerns in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more Nasdaq investment ideas?
If Nasdaq has sharpened your focus, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities that fit your style.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Nasdaq might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com


Leave a comment